How to deduct fit-out costs in 2026
Interior build-out work can usually be written off in year one under the restored 100% bonus depreciation. Exterior work and landlord-funded work cannot.
- Words
- Colm Brady
- Filed
- Read
- 7 min
In 2026, most interior fit-out costs a tenant pays for can be deducted in the first year. Interior work usually counts as qualified improvement property, which is eligible for 100% bonus depreciation on property acquired after January 19, 2025. Section 179 offers a second route. Exterior work and anything the landlord pays for follow different rules.
That is a big change from a few years ago, when a tenant could wait decades to recover the cost of new walls and ceilings. It also means the way you split a fit-out budget into line items now matters for your tax bill, not just your schedule.
This how-to is for business owners paying for their own build-out in leased retail, restaurant or office space. It explains how to deduct fit-out costs under the current rules, how to sort a contractor's quote into the right buckets, and the traps that push costs into slow write-offs.
Can you deduct fit-out costs in the first year?
Usually, yes. If you paid for the work and it improves the inside of an existing commercial building, it is likely qualified improvement property. That property can take 100% bonus depreciation if it was acquired and placed in service after January 19, 2025. You can also elect Section 179 instead, within its limits.
The Internal Revenue Service (IRS) sets out both routes in Publication 946, How to Depreciate Property. It confirms that P.L. 119-21, known as the One Big Beautiful Bill Act, reinstated the 100% special depreciation allowance. It also lists the Section 179 limit for tax years beginning in 2026 as $2,560,000. That limit starts to shrink once total qualifying purchases pass $4,090,000.
For most small tenants, neither cap comes close to binding. A typical café or office fit-out runs well under $1 million. The practical question is not "how much can I deduct," but "which parts of my build-out qualify."
What counts as qualified improvement property
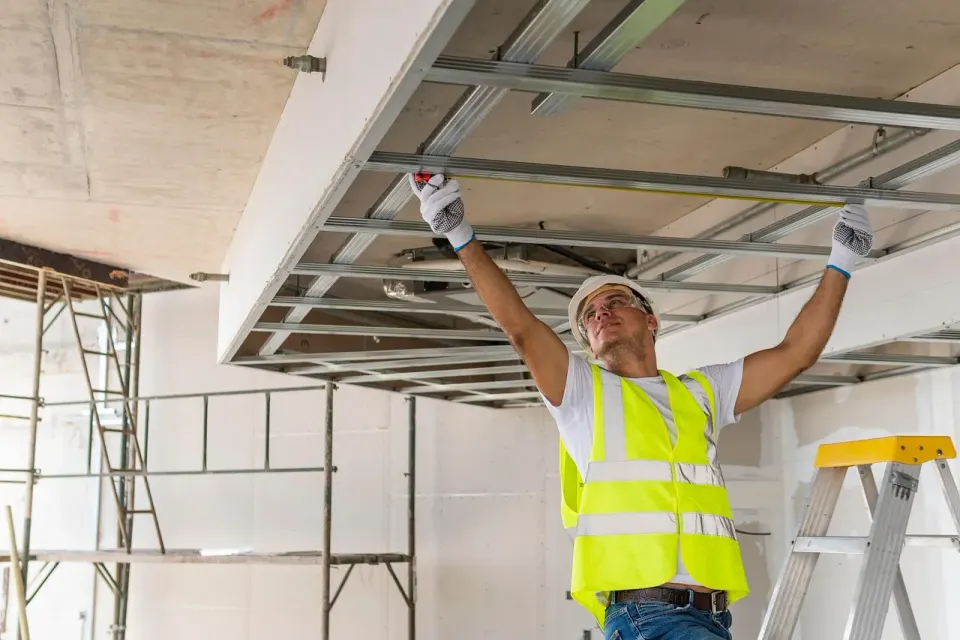
Publication 946 defines qualified improvement property as an improvement to an interior portion of a nonresidential building, made after the building was first placed in service. In plain terms, it is the work you do inside a building that already exists. It has a 15-year recovery period, which is what makes it eligible for bonus depreciation.
The definition also has three exclusions. These items do not count, even when they sit inside the building:
- Any enlargement of the building, such as adding a mezzanine floor
- Elevators and escalators
- The internal structural framework, such as load-bearing walls and beams
Everything else inside the four walls usually qualifies. That covers partition walls, ceilings, interior doors, lighting, flooring, plumbing fixtures and much of the HVAC distribution inside your space. If a contractor lumps "structural work" into one line, ask them to separate anything that is not load-bearing.
Section 179 reaches a few items that sit outside that definition. Publication 946 lists heating, ventilation and air conditioning property, fire protection and alarm systems, and security systems as qualified section 179 real property when they improve a nonresidential building. That matters if your lease makes you replace a rooftop HVAC unit or install a new alarm panel as part of the fit-out.
How to sort a fit-out quote into tax buckets
The single most useful step is to get your contractor's quote broken out by category before work starts. Contractors price by trade, such as framing, electrical and finishes. Your accountant needs it by tax treatment. Asking for both views up front costs nothing and saves hours at year-end.
The table below shows how a hypothetical $180,000 café fit-out might sort. The figures are illustrations for planning, not tax advice.
| Line item | Cost | Likely category | Typical first-year treatment |
|---|---|---|---|
| Partitions, ceilings, lighting, flooring, restroom | $120,000 | Qualified improvement property | 100% bonus or Section 179 |
| Espresso machines, refrigeration, furniture | $45,000 | Equipment (5- or 7-year property) | 100% bonus or Section 179 |
| Storefront and exterior facade | $10,000 | Nonresidential real property | 39-year straight line |
| Signage | $5,000 | Depends on how it is attached | Ask your accountant |
In this example, about $165,000 of the $180,000 could be written off in the first year. The $10,000 storefront would be deducted at roughly $256 a year for 39 years. That gap is why exterior work deserves a hard look in the lease negotiation, not just the budget.
Who paid for it decides who deducts it
You can only depreciate improvements you own and paid for. If the landlord funds the work and keeps ownership, the landlord takes the deduction. This is where the tenant improvement allowance comes in. It reduces your cash outlay, but it can also reduce what you can write off.
The tax treatment of an allowance depends on the lease wording. Some leases say the landlord owns all improvements. Others treat the allowance as a payment to the tenant, who then owns the work. Your accountant will want to see the exact clause, so send it before the lease is signed if you can.
Broker fees can matter here too. A landlord paying a large commission may offer a smaller allowance in return. Our explainer on tenant rep broker fees and who pays them shows how those costs trade against each other inside the deal. A bigger allowance is not always the better outcome once the tax side is counted.
Accessibility work has its own tax breaks
Accessibility work inside a fit-out can qualify for extra help. The IRS lets a business of any size deduct up to $15,000 a year for removing architectural barriers. Small businesses can also claim the Disabled Access Credit, worth up to $5,000 a year. The IRS summary of disability-related tax benefits lists the eligibility rules.
Any alteration you make must meet the 2010 ADA Standards for Accessible Design anyway. So it pays to tag accessible restrooms, door hardware and counters as their own lines. Who pays for that work in the first place is a lease question. Our piece on who pays for ADA compliance in a commercial lease covers the clause that decides it.
Steps to plan a tax-efficient fit-out
The order of operations matters more than any single deduction. These are the steps to follow, from lease negotiation to the first tax return after you open:
- Before signing, send the improvements and allowance clauses to your accountant.
- Ask contractors to price by trade and by tax category.
- Keep interior and exterior work on separate lines and invoices.
- Tag accessibility items so they can be claimed separately.
- Record the date each part of the work is placed in service.
- Check whether your state follows the federal bonus depreciation rules.
The last step trips up a lot of owners. Many states do not follow federal bonus depreciation, so the state return may spread the same cost over years. The federal saving is still real. It is just not the whole picture.
What happens if you leave before the lease ends
Leases end early more often than budgets assume. If you move out and leave your improvements behind, you can generally write off any remaining undepreciated cost in that year. With 100% bonus depreciation, there is usually little left to write off.
The bigger cost on exit is often the make-good clause. That is the obligation to strip your fit-out and return the space to its original condition. Demolition gets no special tax treatment, and it can cost a meaningful share of what the build-out did. Price it before you sign, not after you give notice. Owners who expect to stay a decade or more sometimes buy instead of leasing. Our look at when an SBA 504 loan beats renting compares the two on cost.
Why the 2026 rules change fit-out decisions
Construction demand is holding up, which keeps contractor pricing firm. The Census Bureau's monthly construction spending release put nonresidential construction at a seasonally adjusted annual rate of $773.0 billion in August 2026. That was up 1.0% from July. Faster write-offs help offset those prices, but only if the paperwork is set up correctly.
At New Club Cocoon, we see the same pattern on most tenant fit-outs. The budget gets argued line by line, while the tax categories are left to the accountant months later. Flip that order. A single conversation before the lease is signed can move tens of thousands of dollars into the first year.
The practical answer on fit-out deductions
If you pay for interior work in an existing building, you can probably deduct most of it in 2026. Keep exterior work separate, read the allowance clause closely, and ask your contractor for a quote your accountant can use. Then check how your state treats bonus depreciation.
New Club Cocoon's advice is to treat the tax plan as part of the fit-out plan. Every line on the quote has a schedule, a cost and a tax treatment. Get all three right before the first wall goes up.
Reviewed by New Club Cocoon's fit-out desk on October 23, 2026. This article is general information, not tax advice. Confirm your own position with a qualified tax professional.
Can a tenant deduct the cost of a fit-out in the first year?
What does not count as qualified improvement property?
Who claims the depreciation when the landlord pays for the build-out?
What is the Section 179 limit for 2026?
Keep reading
All stories ↗ Six weeks to fit out a corner café The build took six weeks because the hard part, the drawings, approvals and orders, happened in the four months before anyone picked up a tool. By Colm Brady — 5 min
 Make good: the bill that arrives when you leave Restoration clauses sit quietly in a lease for years, then turn into a five-figure invoice in the final month unless you deal with them early. By Colm Brady — 4 min
 Moving an office over one long weekend A 22-person firm left Friday at noon and opened Tuesday at nine in a new building, and almost all of the work happened months before. By June Whitaker — 5 min
 Next in the index — 04 / 19 Leasing — 8 min
ADA compliance in a commercial lease: who actually pays
The Monday memo · free
Subscribe for the Monday memo
One long read, three clauses worth knowing and a note on the market, every Monday morning.
( Tap to say yes )